
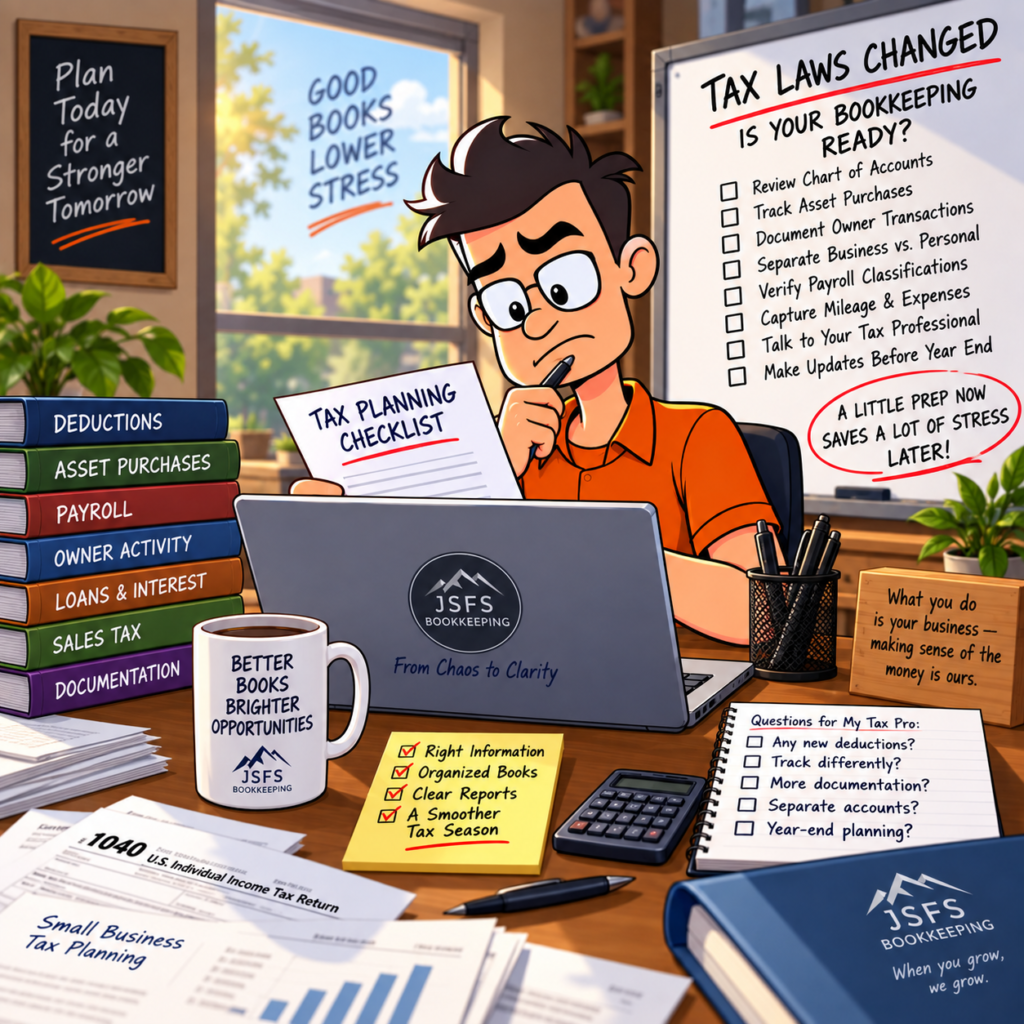
Tax laws change.
That’s nothing new.
But when they do, small-business owners often make the mistake of thinking:
“My tax preparer will take care of that at tax time.”
Your CPA or tax preparer absolutely needs to understand the latest tax rules.
But there’s another piece of the equation that gets overlooked:
Your tax professional can only work with the financial information you give them.
If your bookkeeping isn’t capturing the right information during the year, you may find yourself trying to reconstruct it months later.
Tax Preparation and Bookkeeping Aren’t the Same Thing
This is an important distinction.
Bookkeeping records what happened financially in your business.
Tax preparation determines how those activities should be treated on a tax return.
They are different jobs.
But they absolutely need to communicate with each other.
When tax laws change, your tax professional may need information that wasn’t as important before—or may need information separated differently.
That doesn’t mean your bookkeeper should be giving you tax advice.
It means your bookkeeping needs to be organized well enough that your tax professional can do their job.
Don’t Wait Until January to Ask Whether You Have the Information
Think about some of the transactions that happen throughout a normal business year.
You purchase equipment.
You finance a vehicle.
You take out a loan.
You hire employees.
You pay contractors.
You reimburse mileage.
You contribute money to the company.
You take distributions or draws.
You sell an asset.
You make improvements to a building.
You pay business expenses personally.
You receive money that isn’t actually revenue.
Each transaction may be perfectly legitimate.
The problem comes when everything gets dropped into broad categories without enough documentation to determine what actually happened.
Six months later, someone asks:
“What was this $18,000 payment for?”
That’s when tax preparation starts turning into archaeology.
Recent Tax Changes Make Good Records Even More Important
Federal tax law has undergone significant changes affecting deductions, credits, depreciation and other areas.
Some changes affect individual taxpayers. Others can affect businesses or the owners of pass-through businesses.
That doesn’t mean every change applies to every small business.
It means this is a particularly good year to communicate with your tax professional before the year is over.
Ask them:
Is there anything you need us to track differently?
Are there transactions you want separated?
Do you need additional information about equipment purchases?
Should certain payroll information be tracked separately?
Are there documents we should be collecting now?
Then make sure those requests get communicated to whoever is maintaining your books.
Asset Purchases Are a Great Example
Suppose your business buys a piece of equipment.
From a bookkeeping perspective, we need to know more than:
“I spent $12,000.”
What did you purchase?
When did you purchase it?
When was it placed in service?
Was it financed?
Was there a down payment?
Was there a trade-in?
Were installation or delivery costs included?
Do you have the purchase agreement?
Those details can matter when your tax professional determines the appropriate tax treatment.
If we capture that information when the purchase occurs, the documentation is easy to find.
If we wait until tax season, everyone gets to participate in the annual scavenger hunt.
Owner Transactions Need Attention Too
Another area that creates problems is money moving between a business and its owners.
An owner transfers $5,000 into the company.
Is that revenue?
A loan?
An owner contribution?
Then $2,000 goes back to the owner.
Is that payroll?
A reimbursement?
A loan repayment?
A distribution or draw?
The bank feed tells us that money moved.
It doesn’t tell us why.
That distinction is bookkeeping.
And getting it right gives your tax professional much better information.
Your Chart of Accounts Should Help—Not Hurt
A chart of accounts isn’t something you create once and never touch again.
As a business changes, the chart of accounts may need to change with it.
The goal isn’t to create hundreds of categories.
In fact, too many categories can make financial statements almost useless.
The goal is to capture enough information to make your financial reports meaningful and provide your tax professional with what they need.
Sometimes that means adding an account.
Sometimes it means combining accounts.
Sometimes it simply means creating a better process for documenting transactions.
Talk to Your Tax Professional Before December 31
Tax planning in January is often tax history.
By then, the year is over.
You may still have options, but some decisions simply can’t be changed retroactively.
That’s why we encourage communication between the business owner, bookkeeper, and tax professional during the year.
Your tax professional determines the appropriate tax strategy.
Your bookkeeper makes sure the financial records support that strategy.
And you, as the business owner, get much better information for making decisions.
That’s how the relationship should work.
Good Books Make Tax Season Boring
I say this in different ways all the time, but the principle is simple:
Good bookkeeping isn’t simply recording what happened. It’s making sure the financial records are organized well enough that your business, your tax professional, and you can actually use them.
Tax season shouldn’t involve desperately searching through twelve months of emails, bank statements, receipts, and loan documents trying to figure out what happened.
Most of that work can happen throughout the year.
And when it does, tax season becomes a lot less exciting.
In bookkeeping, boring is often a very good thing.
At JS Full Service Bookkeeping, we work with our clients and their tax professionals so the books aren’t simply finished—they’re useful.
What you do is your business—making sense of the money is ours.
This article provides general bookkeeping information and is not tax advice. Tax laws and individual circumstances vary. Consult your CPA or other qualified tax professional regarding how current tax laws apply to your business.